


 For all latest news, follow the Daily Sun's Google News channel.
Weak appraisal, governance gaps fuel NPLs: BIBM
Cash-flow analysis often inadequate, while policy interventions weaken credit discipline, study finds
Daily Sun Report, Dhaka
Published: 21 Oct 2026, 12:00 AM
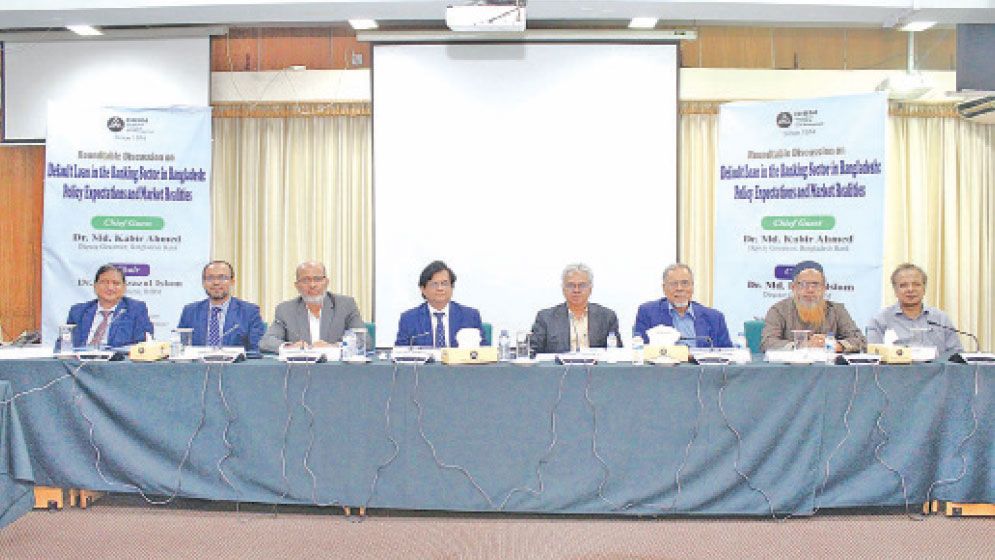
Bangladesh Institute of Bank Management (BIBM) hosts a roundtable at its auditorium on Monday. Researchers, academics, senior bankers, and Bangladesh Bank officials attend. PHOTO: COURTESY
Weak loan appraisals, governance failures in credit approvals, and delayed recognition of non-performing loans (NPLs) are key drivers behind the rising tide of defaulted loans in the banking sector, according to a new study by the Bangladesh Institute of Bank Management (BIBM).
To curb the growing burden of bad loans, the study calls for cash-flow-based assessments, rigorous post-disbursement monitoring, and greater accountability in credit decisions.
The findings were presented Monday during a roundtable titled “Non-Performing Loans in Bangladesh’s Banking Sector: Policy Expectations and Market Realities” at the BIBM auditorium, attended by researchers, academics, senior bankers, and Bangladesh Bank officials.
Highlighting the urgency for reform, BIBM Director General Dr Md Ezazul Islam noted that the study exposes critical gaps in loan quality, credit independence, monitoring, and recovery efforts.
“High NPLs are merely a symptom; our task is to examine the underlying causes and identify implementable reforms,” he stated. Survey data from the study revealed that 68.8% of respondents found cash-flow analysis inadequate during loan appraisals, while 43.8% cited major weaknesses in industry- and sector-specific risk assessments.
The research also found shortcomings in monitoring the use of loan proceeds, collecting reliable cash-flow information and conducting regular inspections of borrowers’ businesses after disbursement.
It identified overdue instalments, unusual transactions, declining cash flows, diversion of loan funds and deteriorating borrower risk profiles as early warning signs of potential defaults.
The study also found that pressure to maintain adequate loan-loss provisions, concerns over management accountability and attempts to present better asset-quality indicators could delay the recognition of defaulted loans.
It stressed that timely identification and recognition of NPLs were essential to ensuring transparency in banks’ actual financial positions.
Related-party lending, regulatory leniency under scrutiny
The study identified related-party lending, involving borrowers connected to a bank’s management or ownership, as a major concern, with 60% of respondents describing it as a significant problem.
Meanwhile, 80% believed regulatory leniency and repeated policy interventions had weakened credit discipline in the banking sector.
However, the researchers cautioned that these findings reflected respondents’ perceptions rather than the actual prevalence of such practices across the industry.
The study noted that while loan rescheduling could help financially distressed but viable businesses recover, it could also be used to improve reported NPL ratios and provisioning indicators without addressing underlying repayment problems.
It recommended more effective use of negotiations and settlements, loan restructuring, collateral recovery, legal proceedings and alternative dispute resolution mechanisms to recover defaulted loans.
The effectiveness of these measures, it said, depended on borrowers’ business viability, repayment capacity and the legal prospects of recovering outstanding dues.
Participants identified weaknesses in implementing credit approval and governance policies as the largest gap between regulatory expectations and banking practices.
Other major gaps involved loan appraisal and the implementation of loan rescheduling and restructuring policies.
The study called for greater transparency in credit approval, stronger risk assessments and effective monitoring to close these gaps and restore lending discipline.
BIBM Director (Research, Development and Consultancy) Prof Md Shihab Uddin Khan delivered the welcome address, while Bangladesh Bank Deputy Governor Dr Md Kabir Ahmed attended the programme as chief guest.